The Safety Features on Your Hyundai That Could Be Quietly Lowering Your Insurance Bill
Most Hyundai owners know their vehicle comes equipped with a range of safety technologies. Fewer of them know that several of those technologies are specifically recognized by insurance carriers as premium-reduction qualifiers — and that a meaningful number of policyholders are paying more than necessary simply because they have never asked the right questions.
This article examines the specific features Hyundai deploys across its lineup, how insurance companies evaluate those features, and the practical steps owners can take to ensure their policy accurately reflects the protection their vehicle already provides.
Why Insurers Pay Attention to Driver Assistance Systems
Insurance pricing is fundamentally a risk calculation. When a vehicle is equipped with technologies that demonstrably reduce the frequency or severity of collisions, the statistical risk profile of insuring that vehicle decreases. Carriers have increasingly incorporated this data into their underwriting models, particularly as the Insurance Institute for Highway Safety (IIHS) and the National Highway Traffic Safety Administration (NHTSA) have published more granular research on the real-world effectiveness of advanced driver assistance systems (ADAS).
The IIHS has documented that front automatic emergency braking reduces rear-end collision rates by approximately 50 percent. Lane departure warning systems have shown measurable reductions in single-vehicle and head-on crash involvement. These are not marginal improvements — they are the kind of actuarial data that shifts how risk is priced.
Hyundai has been an early and consistent adopter of these technologies, and the breadth of its standard safety suite across trim levels means that even owners of entry-level configurations may be driving vehicles with qualifying features.
Hyundai SmartSense: The Core Safety Architecture
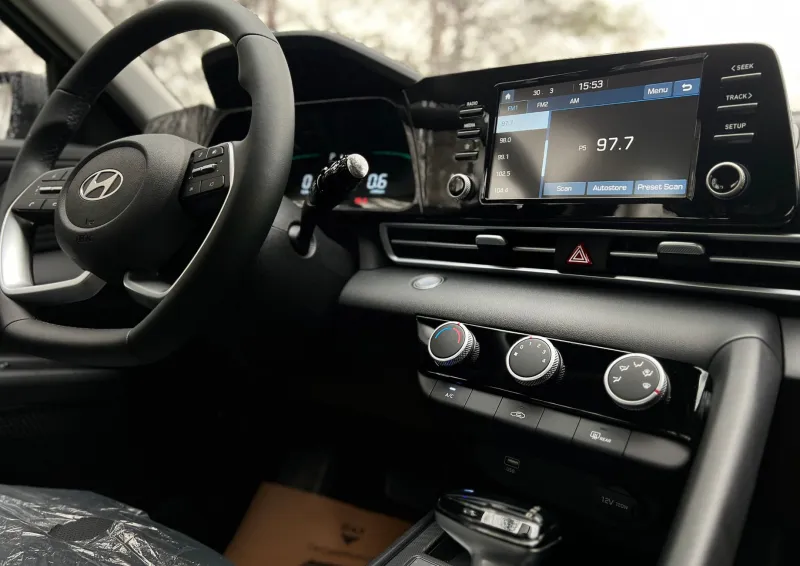
Hyundai groups its primary safety and driver assistance technologies under the SmartSense umbrella. Understanding what is included — and at which trim levels — is the starting point for any insurance conversation.
Forward Collision-Avoidance Assist (FCA) uses radar and camera technology to detect vehicles, pedestrians, and cyclists in the vehicle's path, providing alerts and applying automatic braking when necessary. This feature is standard across a wide range of current Hyundai models, including the Elantra, Tucson, Santa Fe, and Sonata, beginning at base trim levels.
Lane Keeping Assist (LKA) and Lane Departure Warning (LDW) monitor lane markings and provide corrective steering input or driver alerts when unintentional lane drift is detected. These systems are among the most widely recognized by insurers for discount qualification.
Blind-Spot Collision Warning (BCW) alerts drivers to vehicles in adjacent lanes that may not be visible in mirrors — a particularly relevant technology for highway driving, where lane-change collisions are disproportionately represented in accident statistics.
Driver Attention Warning (DAW) monitors driving patterns for signs of fatigue or inattention and prompts the driver to take a break. While fewer insurers currently discount specifically for this feature, it is increasingly being evaluated as ADAS data matures.
Rear Cross-Traffic Collision Warning and Surround View Monitor features, available on higher trims of the Tucson, Santa Fe, Palisade, and Ioniq models, address the backing and low-speed maneuvering scenarios that generate a significant share of parking lot and residential street claims.
Which Features Insurers Are Most Likely to Recognize
Not every safety technology translates directly into a line-item discount, and the recognition process varies considerably by carrier. However, the features that most consistently appear in insurance discount programs include:
- Automatic emergency braking (AEB) — recognized by the majority of major US carriers
- Lane departure warning and lane keeping assist — widely recognized, particularly by carriers using IIHS data as a pricing reference
- Blind-spot monitoring — recognized by a growing number of carriers, especially for vehicles with highway-heavy usage profiles
- Adaptive cruise control with stop-and-go capability — recognized by progressive carriers as a fatigue-reduction and following-distance technology
- Anti-lock braking systems (ABS) and electronic stability control (ESC) — these have been standard for years but remain discount-eligible with some carriers that have not updated owner records
The discount amounts themselves vary from 2 to 15 percent depending on the carrier, the specific feature, and the state in which you are insured. In states with competitive insurance markets — Texas, Florida, Ohio, and Pennsylvania among them — the variation between carriers on ADAS recognition can be substantial.
The Verification Process: What Owners Should Actually Do
The most common reason Hyundai owners miss available discounts is not that their insurer refuses to offer them — it is that the policy was written without a detailed feature audit, and no one has revisited it since.
The following checklist provides a structured approach to closing that gap:
Step 1: Pull your vehicle's window sticker or build summary. This document lists every factory-installed feature and is the authoritative source for what your vehicle includes. If you no longer have the original sticker, Hyundai's owner portal or a VIN decoder can reconstruct the feature list.
Step 2: Contact your insurance carrier directly. Ask specifically which ADAS features they recognize for premium discounts and request that your policy record be reviewed against your vehicle's actual configuration. Do not assume the agent who wrote your original policy conducted this review.
Step 3: Request a written policy endorsement if discounts are applied. Verbal confirmations during a phone call are not sufficient. Any discount adjustments should appear in your written policy documentation.
Step 4: Compare at renewal. Insurance carriers update their ADAS discount programs periodically, and features that were not previously recognized may become eligible. Treat each renewal as an opportunity to re-verify rather than a routine auto-pay event.
Step 5: Shop competitively if your current carrier's recognition is limited. Not all carriers have invested equally in ADAS discount infrastructure. If your vehicle is equipped with a comprehensive SmartSense suite and your carrier recognizes only one or two features, a competing carrier may offer meaningfully better pricing for the same coverage levels.
A Note on Hyundai's Newer Electrified Models
Owners of Hyundai's Ioniq 5, Ioniq 6, and Tucson or Santa Fe hybrid variants have an additional consideration. Several insurers have begun incorporating EV-specific safety data — including the lower center of gravity that reduces rollover risk and the regenerative braking behavior that reduces rear-end collision frequency — into their underwriting models. If you own one of these vehicles, it is worth raising the question of EV-specific safety recognition explicitly with your carrier, as this is an area where policy language has not always caught up with underwriting practice.
The Bottom Line
Hyundai has invested substantially in making its vehicles among the safest on American roads. The responsibility for ensuring that investment is reflected in your insurance premium, however, rests with you. A single phone call to your carrier, armed with your vehicle's feature list, can initiate a review that puts real money back into your pocket — and in many cases, that conversation has never happened.